

Deferit: Split Bills, Pay in 4
Deferit
- 4.5
- 2.29K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
Deferit: Split Bills, Pay in 4 Pros and Cons
Pros
- Helps spread eligible bills across several scheduled payments.
- Payment reminders can make recurring expenses easier to track.
- Useful budgeting option when income arrives at different times.
- Simple interface makes setting up a payment plan relatively quick.
- May reduce the need to borrow from friends or use high-interest credit.
Cons
- Eligibility and available features may vary by location and account history.
- Late payments could lead to fees, restrictions, or account consequences.
- Not every biller or expense type may be supported by the service.
- Splitting payments can make it easier to underestimate total monthly spending.
- Requires linking payment details and sharing personal financial information.
 Analysis by All-app
Managing several bills at once can be harder than the total amount suggests. The problem is often timing: rent, utilities, insurance, phone service and other regular expenses may arrive before the next paycheck. I tested Deferit: Split Bills, Pay in 4 with that situation in mind, and I found that its value is less about making bills cheaper and more about giving a tight month a more orderly shape.
This is a free finance app from Deferit, aimed at people who want to divide eligible bill payments into four smaller, interest-free instalments. It is available to an Everyone audience, runs on Android 7.0 or later, and its current version is 3.0.6. The app has reached over one million installs, with a 4.5 average from around twenty thousand ratings and roughly two thousand three hundred written reviews. Those figures suggest that the idea is easy to understand, although the real question is whether the workflow fits the way you already manage money.
How the basic bill-splitting workflow feels
The first thing I noticed is that Deferit is built around a very specific job: helping you handle a bill now while spreading your repayment across four smaller payments. That makes it different from a general budgeting app. You are not opening it mainly to categorize spending, build a long-term financial plan or watch investment balances. You open it because a bill needs attention and your available cash is arriving in stages.
The sensible starting point is to gather the bill details before opening the app. Have the amount, due date and payment information ready, and check that the bill is one you genuinely need to manage rather than an optional purchase. This small preparation matters because splitting a payment can feel reassuring enough to encourage rushed decisions. I found the app works best when it is used as a deliberate cash-flow tool, not as permission to add more commitments.
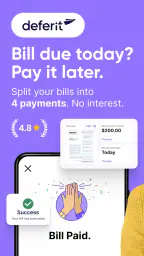
The central promise is straightforward: the bill is divided into four payments without interest. That can be useful when a regular expense lands a few days before payday. Instead of allowing one large withdrawal to disrupt food, transport or other essentials, you can plan around smaller scheduled amounts. The benefit is practical rather than magical; the full obligation still exists, and the instalments still need to fit your later income.
A realistic example would be a household bill that arrives during a week when several other direct debits are due. I would first compare the four planned payments with my next paydays, then check whether the first payment leaves enough for essentials. If the later instalments overlap with another unusually expensive week, I would not use the split simply because the first payment looks manageable. The app can smooth timing, but it cannot repair a budget that is already short every month.
That distinction is important when comparing Deferit with the usual alternatives. A credit card may offer a larger spending limit and broader flexibility, but it can introduce interest, revolving debt and more complicated repayment decisions. A traditional budgeting app gives better visibility across all income and expenses, but it does not itself divide a bill into four payments. Saving a small buffer is usually cleaner when you have enough time to build one. Deferit sits between those choices: more immediate than saving, more focused than a budgeting dashboard, and less suitable for open-ended spending.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What I would check before confirming a bill
I would treat the confirmation screen as a planning checkpoint rather than a formality. Look at the total obligation, the timing of every instalment and the account that will be used for repayment. The first payment is only one part of the decision. A plan that looks comfortable today may become awkward when a later payment lands beside rent, a subscription renewal or a seasonal expense.
One useful habit is to write the four dates in the same place where you track other bills. This prevents the app from becoming a separate memory system that you rarely open. If your bank app supports reminders, calendar entries or notifications, use those alongside the Deferit schedule rather than relying on memory alone. The strongest workflow is not merely “split the bill”; it is “split it, record it and reserve for the next instalment.”
I also recommend separating essential bills from convenience spending. Deferit makes most sense for a necessary expense with a predictable amount and a clear repayment plan. It is a weaker fit for impulse purchases, uncertain costs or anything you would struggle to pay even after dividing it. The four-part structure can reduce the shock of one payment, but it should not hide the fact that your future income is already committed.
Settings and routines worth checking
Experienced use begins with the practical settings around repayment rather than with clever tricks. Before using the service repeatedly, I would review the payment method, notification preferences and any account details that affect how you receive reminders or complete scheduled payments. The exact options available can depend on the app version and device, so I would read each screen carefully instead of assuming every account has identical controls.
Notifications deserve particular attention. If reminders are too quiet, a scheduled instalment can become an avoidable surprise. If they are too frequent, you may start dismissing them automatically. I prefer a simple routine: keep the important repayment reminders active, then check the schedule during my normal weekly money review. Notifications should prompt action, not replace it.
Another setting-related habit is keeping contact and billing information current. When an app is used for recurring financial tasks, an old email address, expired payment method or outdated phone number can create friction at exactly the wrong time. I would review these details whenever I change banks, replace a card or move home. That is not a Deferit-specific gimmick; it is a sensible safeguard for any service handling scheduled payments.
The developer is Deferit, and the app’s finance focus is clear, but I would still approach it with the same care as any financial service. Use a strong device lock, avoid signing in on a shared phone and do not forward account messages casually. The Everyone content rating describes the audience suitability, not the absence of financial responsibility. Adults should still make the repayment decision with a complete view of their budget.
One non-obvious advantage of checking settings early is that it helps you decide whether Deferit can become a repeatable tool rather than a one-off rescue. If you can see reminders clearly, keep your payment details current and record each plan in your usual system, the app is easier to manage. If you prefer all financial activity to stay inside one bank account or one budgeting platform, adding another service may create more administration than relief.
Faster patterns that do not sacrifice control
Once the basic workflow is familiar, speed comes from preparation rather than rushing through screens. I would keep a small note containing the biller name, the usual amount and the normal due period for recurring expenses. When a new bill arrives, I can compare it with that note quickly and spot unusual changes before deciding whether to split it. This is especially helpful for utilities, where the amount may vary.
A second useful pattern is choosing one weekly money check-in. During that session, I would review upcoming Deferit instalments together with ordinary direct debits and card payments. Looking at them in one list reveals conflicts that are easy to miss when each payment is viewed separately. It also reduces the temptation to open the app only when a reminder appears, which is often too late for proper planning.
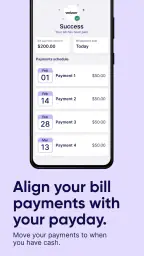
For people paid on a regular schedule, matching each instalment to a specific pay cycle can make the plan easier to understand. I would label the purpose in my notes, such as “utility bill, second payment,” rather than recording only the amount. That small detail helps prevent confusion when several split bills are active. It also makes it easier to decide whether taking on another plan would overload the same future paycheck.
Families or partners should agree on who is responsible for checking the schedule. A split bill can be missed when one person assumes the other is monitoring it. The app may organize the payment plan, but it cannot resolve unclear household ownership. A shared calendar or a simple household money note can make the arrangement much safer.
There is also a useful trade-off between speed and verification. If the bill is familiar, the process may feel quick. If the amount, due date or provider information has changed, slowing down is worthwhile. I would never use a saved routine as a reason to approve an unfamiliar charge automatically. The fastest reliable workflow is the one that repeats the checks that prevent expensive mistakes.
Where the four-payment model reaches its limits
The biggest limitation is structural: four smaller payments are still four obligations. If your income is irregular, the schedule may be harder to manage than one payment because it creates several future dates to remember. Someone paid weekly may find the arrangement comfortable, while someone waiting on unpredictable freelance income may prefer to negotiate a bill, use an existing emergency fund or speak directly with the provider.
Deferit is also not a substitute for a full emergency fund. A split plan can help with timing, but it does not create extra income. If every month requires several bills to be divided, that is a sign to examine the underlying budget. In that situation, a nonprofit debt adviser, a conversation with the bill provider or a broader spending plan may be more appropriate than adding another instalment schedule.
I would also skip it when the bill is already affordable without assistance. Adding a repayment calendar for convenience can make a simple expense harder to track. Likewise, if you know you tend to forget scheduled payments, the app will not solve that behavior by itself. You need a reminder routine and enough money reserved for each date.
Another limitation is that the app is focused on a narrow financial moment. It may help divide a bill, but it is not the place I would expect to perform a complete household review. For detailed categories, long-term goals, debt snowball planning or cash-flow forecasting across all accounts, a dedicated budgeting tool may be better. For a bill that needs to be broken into four interest-free payments, Deferit is more directly relevant.
I would read the current terms and payment details inside the app before relying on any plan, particularly if the bill is urgent. Financial products can involve account-specific conditions, eligibility checks or consequences around missed payments, and those details matter more than the attractive simplicity of the headline idea. The safest approach is to understand the exact commitment shown on your own screen.
My verdict after building a repeatable routine
After using the app as a focused bill-management tool, I see its strongest quality in its narrow purpose. It does not try to be a complete financial command center. Instead, it gives people a way to divide a bill into four smaller, interest-free payments when the main problem is timing. That clarity makes it easier to decide whether the service belongs in your routine.
I would recommend it to someone with predictable income who occasionally faces a large essential bill at an inconvenient point in the month. It can also suit households that already track their spending and want an additional way to smooth specific payments. The best users will be comfortable checking dates, reserving money and treating each instalment as a real commitment.
I would not recommend making it the default answer to every financial squeeze. If your budget is consistently negative, if your income changes sharply from week to week or if you already have too many repayment dates, splitting more bills may increase pressure. In those cases, a savings buffer, direct negotiation with providers or independent financial guidance is likely to address the cause more effectively.
The app is free to download, which lowers the barrier to trying its workflow, but “free” should not be confused with cost-free financial responsibility. The important question is whether the repayment schedule works for you. I would judge it by the complete plan, not by the size of the first payment or by how quickly the setup can be completed.
Its release on October 28, 2021, and continued presence through version 3.0.6 show that this is an established app rather than a brand-new experiment. Still, I would keep the app updated and review the information presented during each new bill setup. Familiarity is useful, but financial habits should never become automatic to the point that you stop checking the details.
My final view is positive but measured. Deferit is most useful when it turns one awkward bill into a clearly scheduled plan, not when it disguises an unaffordable lifestyle. Used alongside reminders, a weekly cash-flow check and honest limits on future commitments, it can be a practical addition to a finance routine. Used without those habits, the same four-payment structure can simply move today’s stress into several later dates.
Frequently Asked Questions
What is Deferit: Split Bills, Pay in 4?
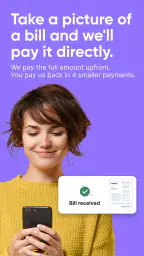
Deferit is a bill-payment and budgeting app designed to help users manage eligible bills through flexible payment options. Depending on your location and account eligibility, it may allow you to split certain bills into smaller scheduled payments or pay them in four installments. The app is intended to make recurring expenses easier to organize, but it is not a replacement for careful budgeting or an emergency fund.
How does Deferit’s bill-splitting or Pay in 4 feature work?
After creating an account, you generally add an eligible bill and review the available repayment schedule before confirming. Deferit may pay the bill on your behalf while you repay the service according to the displayed plan, or it may divide a purchase into four scheduled installments. The exact process, payment dates, limits, and available features can vary by country, user history, bill type, and approval decisions.
Are there fees, interest charges, or late-payment penalties?
Before using Deferit, carefully review the total cost shown in the app because fees and conditions can depend on your plan, location, and account status. Some services may charge membership, processing, expedited-payment, or other account-related fees, while installment plans may have separate terms. Missing a scheduled payment could also lead to penalties, restrictions, or collection activity, so confirm every cost before accepting.
What bills and purchases are eligible, and are there spending limits?
Eligibility is not necessarily the same for every user. Deferit may support common household bills or selected purchases, but some providers, bill categories, transaction types, or payment amounts may be excluded. Your account can also have limits based on verification, repayment history, location, and other risk checks. The app should show whether a bill qualifies and the maximum amount available before you submit it.
Is Deferit safe to use, and what information is required?
Deferit may request personal, contact, billing, payment, and identity information to verify your account, assess eligibility, process payments, and manage repayments. Use the official app-store listing and check the developer details before downloading. Enable available security features, read the privacy policy and terms, and avoid sharing login codes. Remember that approval is not guaranteed, and responsible use is important because missed repayments can affect your finances.


